A simple SIP, started early and left to grow, can fund a monthly pension for life — here's the math behind it.
Most people delay retirement planning because it feels distant, complicated, or unaffordable. But the numbers tell a different story. A disciplined monthly SIP of just ₹15,000, growing at an assumed 12% CAGR, can snowball into a corpus large enough to pay a monthly pension — and keep growing even after the withdrawals begin.
The three stages of the plan
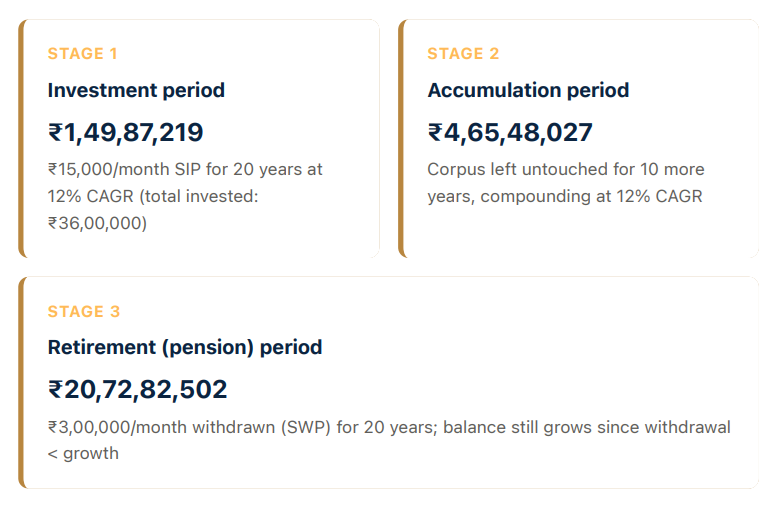
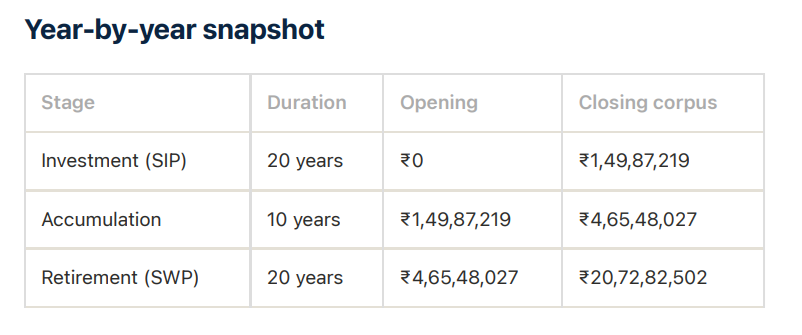
The key insight: once the corpus is large enough, its annual growth (12% of the balance) can exceed the annual pension withdrawn. In this illustration, the corpus generates about ₹56 lakh in growth in the first retirement year alone — well above the ₹36 lakh withdrawn — so the pension becomes sustainable indefinitely rather than depleting the capital.
Why retirement planning matters
- Compounding needs time, not just money. The first 10–15 years of a SIP contribute far less to the final corpus than the last few — starting early is more powerful than investing more later.
- Inflation erodes a static income. Without a growing corpus, a fixed pension loses purchasing power every year; a corpus that keeps compounding protects against this.
- Rising life expectancy means longer retirements. A 20–30 year retirement is now common, and outliving your savings is a real risk without proper planning.
- Healthcare costs rise with age. A larger, still-growing corpus provides a cushion for medical and unplanned expenses in later years.
- Discipline beats timing. A monthly SIP removes the guesswork of "when to invest" and builds the habit that ultimately funds retirement.
Note: All figures are illustrative projections based on an assumed 12% CAGR and are not guaranteed. Actual mutual fund returns will vary with market conditions.
Sri Wealth Investments · AMFI Registered Mutual Fund Distributor (ARN-103277) ·
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.